Summary
Discover several effective strategies for paying for assisted living without selling your house, allowing you to preserve this meaningful family asset while securing the care and support you need.
- Access home equity through reverse mortgages or home equity lines of credit, though each option has different repayment requirements and eligibility considerations
- Generate rental income from your family home through long-term rentals, short-term rentals, or professional property management services to help offset monthly expenses
- Explore long-term care insurance, veterans benefits, life insurance riders, and retirement income sources that may cover assisted living costs
- Withdraw from retirement accounts like IRAs and 401(k)s, or utilize investment income such as dividends and annuities to supplement monthly payments
- Consider family contributions, bridge loans, or life estate arrangements as creative financing solutions, with guidance from a financial planner or elder law attorney
For many families, the family home represents more than property. It holds decades of memories, provides financial security, and may be something you hope to pass down to your children. When considering assisted living, selling the house might seem like the only way to cover expenses.
Fortunately, several strategies exist for paying for assisted living without selling your house. Understanding these options can help you preserve a meaningful family asset while planning for the support you or a loved one needs.
Using Home Equity Without Selling
One approach when considering how to afford assisted living and keep your house is to access home equity while maintaining ownership.
Reverse Mortgages
A reverse mortgage allows eligible homeowners aged 62 and older to convert home equity into cash. However, these loans generally require the borrower to maintain the property as a principal residence. A permanent move to assisted living may trigger repayment, making this option unsuitable for some families.
Home Equity Lines of Credit
A home equity line of credit (HELOC) allows homeowners to borrow against their property's value as needed. Unlike a reverse mortgage, a HELOC typically requires monthly payments.
Before choosing either option, review repayment requirements, borrowing costs, and how the move could affect eligibility.
Rental Income Strategies
Turning your family home into a rental property can provide income to offset assisted living expenses.
For families considering keeping the family home while in assisted living, rental income offers several possibilities:
- Long-term rentals: Generate recurring monthly income while maintaining ownership.
- Short-term rentals: May produce additional income in desirable locations but require more frequent management.
- Property management services: Help coordinate tenant communication, maintenance, and other responsibilities.
Rental income isn't guaranteed, and expenses such as repairs, insurance, taxes, and vacancies should be included in your calculations.
For Cedarburg families, keeping a property nearby may also preserve familiar connections while a loved one settles into community living.
Long-Term Care Insurance and Benefits
Existing insurance policies and available benefits may help families manage assisted living costs without a home sale.
Long-term care insurance can cover eligible assisted living expenses, depending on the policy. Review coverage limits, waiting periods, and reimbursement requirements before making financial decisions.
Additional resources worth exploring include:
- Veterans benefits: Eligible veterans and surviving spouses may qualify for VA Aid and Attendance benefits.
- Life insurance: Some policies include accelerated death benefits or long-term care riders.
- Retirement income: Pensions, Social Security, and other recurring income sources may help cover monthly expenses.
These resources can reduce the amount families need to draw from savings or property assets.
LakeHouse Cedarburg also offers a Military Veterans Program with savings opportunities for eligible veterans. Families can ask the community about program details when discussing their budget.
Investment Income and Retirement Accounts
Retirement savings and investment income offer additional ways of financing senior living without selling property.
Withdrawals from IRAs and 401(k)s can supplement monthly income. Required minimum distributions may also provide funds, depending on the account holder's age and applicable rules.
Other potential income sources include dividends, bonds, and annuities. However, investment returns can fluctuate, and withdrawals may affect taxes or long-term savings.
A financial advisor can help families determine which resources to use first and how to maintain financial flexibility.
Family Support and Creative Financing Solutions
Sometimes, several smaller contributions make assisted living more manageable.
Adult children may agree to share monthly expenses, allowing loved ones to keep ownership of the family home. Clear conversations about contribution amounts and expectations can help prevent misunderstandings.
Other alternatives to selling a house for assisted living include bridge loans and certain estate-planning arrangements.
Bridge loans provide temporary financing but require a repayment plan. Life estate arrangements may preserve certain property interests, although they can affect ownership rights and eligibility for public benefits.
Consult an elder law attorney before transferring property or making significant ownership changes.
Planning Your Financial Path Forward
Finding the right payment strategy starts with understanding actual expenses and available resources.
Consider these steps:
- Review your finances: Compare monthly income, savings, insurance benefits, and property expenses.
- Consult professionals: Speak with a financial planner and elder law attorney about financing and ownership decisions.
- Explore community pricing: Understand what monthly fees include and which services may cost extra.
- Plan early: Give your family time to evaluate options without rushing important decisions.
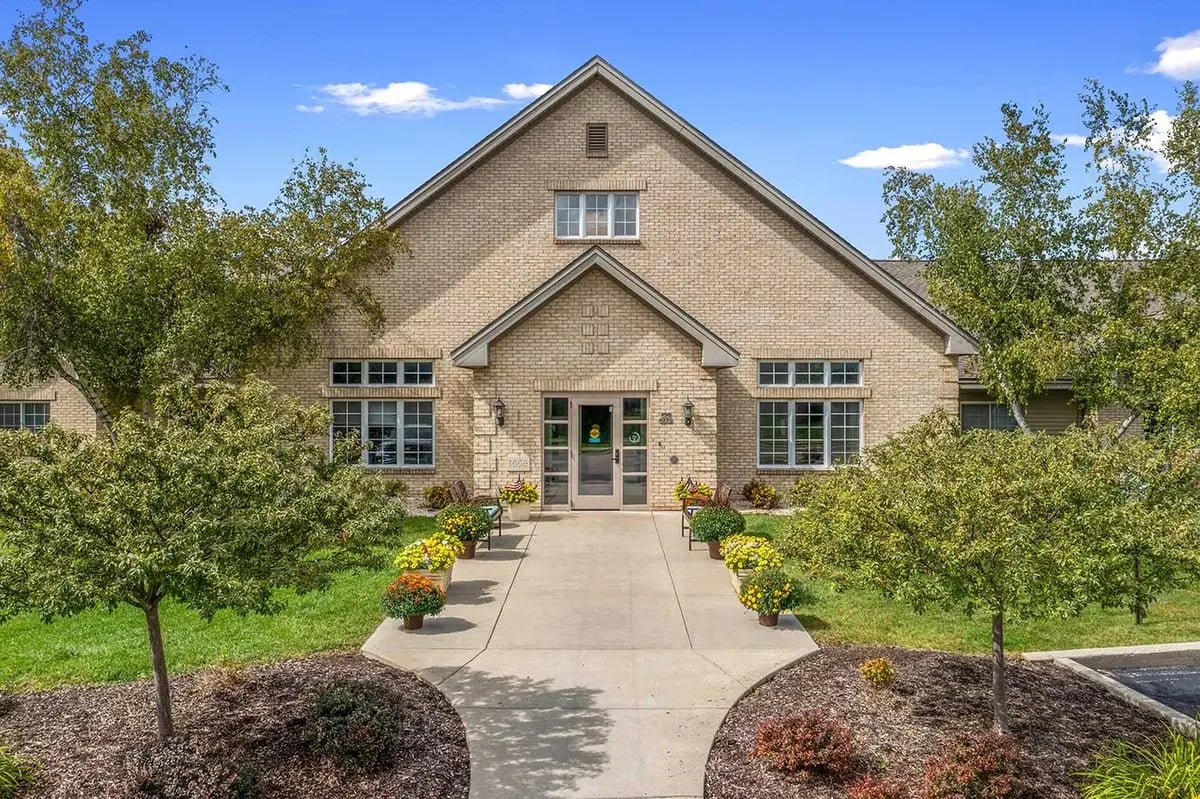
At LakeHouse Cedarburg, Assisted Living includes personalized support with daily tasks, chef-prepared meals, weekly housekeeping, and scheduled transportation. Residents can also enjoy a private courtyard, walking paths, and welcoming spaces for gathering with neighbors.
These everyday conveniences matter when comparing the cost of maintaining a house with the expenses of community living.
Families can explore assisted living options and community amenities to better understand what is available.
Explore Assisted Living Payment Options in Cedarburg, WI
Keeping the family home while arranging assisted living may be possible with thoughtful financial planning. The right approach depends on your income, property obligations, and long-term goals.
At LakeHouse Cedarburg, we're happy to answer questions about our Assisted Living community, available services, and pricing.
Schedule a tour to explore the community, discuss your family's needs, and learn more about your options.